Does Homeowners Insurance Cover a Burst Pipe in Simpsonville, SC?
The Water’s Off, But Now You’re Wondering What Insurance Will Cover
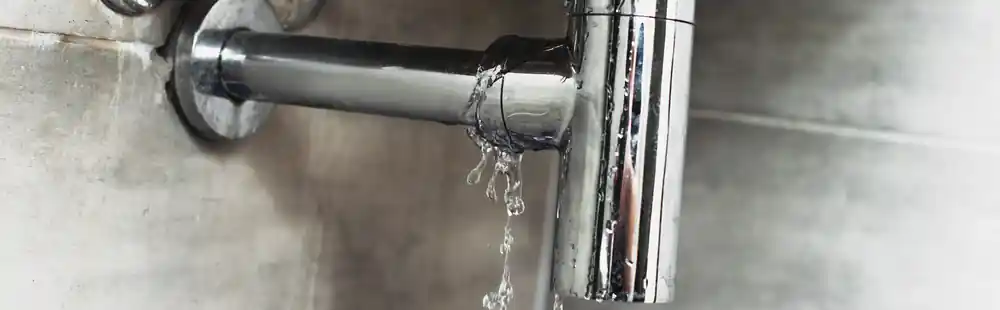
The pipe has burst, the immediate panic has faded, and you’ve stopped the water from flowing everywhere. Now you’re staring at the damage wondering if your homeowners insurance is actually going to cover this or if you’re facing the full bill yourself. Whether homeowners insurance covers a burst pipe in Simpsonville, SC depends on a few specific factors insurance companies look at closely, and understanding them before you file a claim can save you a frustrating surprise. Call 864-263-2847 if you need a professional assessment of the damage before you call your insurer.
Most Policies Cover Sudden Bursts, But Not Neglected Leaks
A burst pipe is typically covered by homeowners insurance when the burst was sudden and accidental, meaning it happened without warning rather than as a result of something a homeowner could have prevented or noticed earlier. This distinction matters because insurance companies treat a pipe that fails in the middle of the night completely differently from a pipe that’s been slowly leaking for months before finally giving way.
That word, sudden, is what most insurers focus on when deciding whether to pay. A pipe that bursts without prior warning fits the definition cleanly. A pipe showing visible signs of a slow leak for an extended period before failing is where claims start getting complicated. If water was dripping or pooling for weeks, and that damage is now part of the claim, an insurer may argue the homeowner had a responsibility to address it sooner, which can result in a partial denial or a request to cover only the most recent damage.
Document Everything Before You File
Photos and clear timing matter far more than most homeowners realize when an insurance claim gets reviewed. Taking pictures of the water damage as you find it, the affected walls or ceiling, and the pipe itself if it’s accessible, creates a record that supports the “sudden and accidental” argument before cleanup and repairs start covering up the evidence.
- Photograph the water damage and the burst pipe itself before cleanup starts
- Note the approximate time you discovered the burst, as early as possible
- Write down whether there were any earlier signs, like a slow drip or reduced pressure, or if this came completely out of nowhere
- Keep any invoice or written assessment from the plumber who diagnosed what caused the failure
- Contact your insurer promptly rather than waiting to see how much cleanup will cost
A plumber’s written diagnosis of what caused the burst is particularly valuable to your claim. Insurance adjusters aren’t plumbing experts, and they rely heavily on professional documentation explaining whether the failure was a freeze, a corroded joint, a manufacturing defect, or age-related wear. That documentation gives your claim a much stronger foundation than homeowner speculation about what happened.
Warmer Water & Plumbing Provides the Documentation Your Claim Needs
A clear professional assessment of what caused a burst pipe gives you something solid to bring to an insurance conversation, rather than a guess or an adjuster’s assumption about what might have happened. That diagnosis also answers the harder question, whether the failure was truly sudden or the result of a longer-developing issue, since that distinction often determines how fairly a claim gets handled.
Get Your Damage Assessed Before You Call the Insurer
A burst pipe is stressful enough without also guessing at what your insurance will or won’t cover. Professional documentation from the moment a burst is discovered supports your claim far better than trying to explain things after the fact with no evidence to back it up. If you’re in Simpsonville dealing with a burst pipe right now, call 864-263-2847 and get the assessment and documentation you need before that conversation with your insurer happens.
0 Comments